Bybit X Block Scholes crypto derivatives analytics report (May 22, 2025): Bitcoin options skew steepens toward calls by 7%; ETH outperformances moderate
AI Summary
Show More
Quickly grasp the article's content and gauge market sentiment in just 30 seconds!
Key Highlights:
Our weekly crypto derivatives analytics report delves into macro events; the current state of crypto and trading signals from spot trading volume; and futures, options and perpetual contracts.
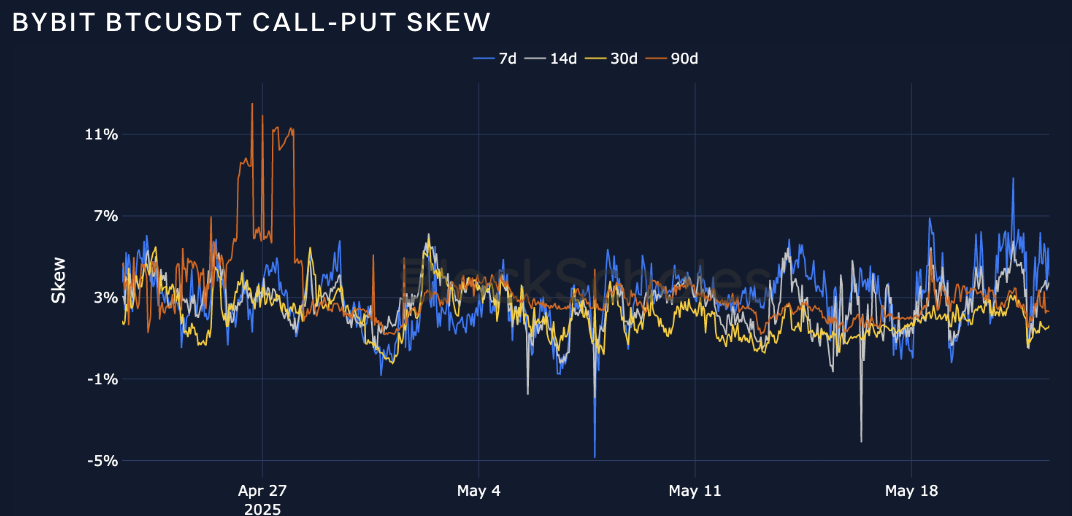
Front-end volatility for BTC has reacted to recent spot price fluctuations, leading to a new all-time high (ATH) of $111.8K, the first since January 20, 2025. At-the-money implied volatility is between 45% and 50%, with short-tenor volatility rising from last week's lows. Perpetual funding rates remain stable, even as spot prices climb, though options skew steepened towards calls by 7% due to increased demand for OTM calls.
In perpetual swaps, open interest hit a new May high over $11B, reflecting stronger risk-on sentiment than in April. For ETH, short-tenor options retain their volatility premium compared to longer-tenor options, while OTM calls continue to show solid support, despite a slowdown in the recent surge of ETH’s spot price.
Please check out the report’s highlights.
Perp reaches all-time high
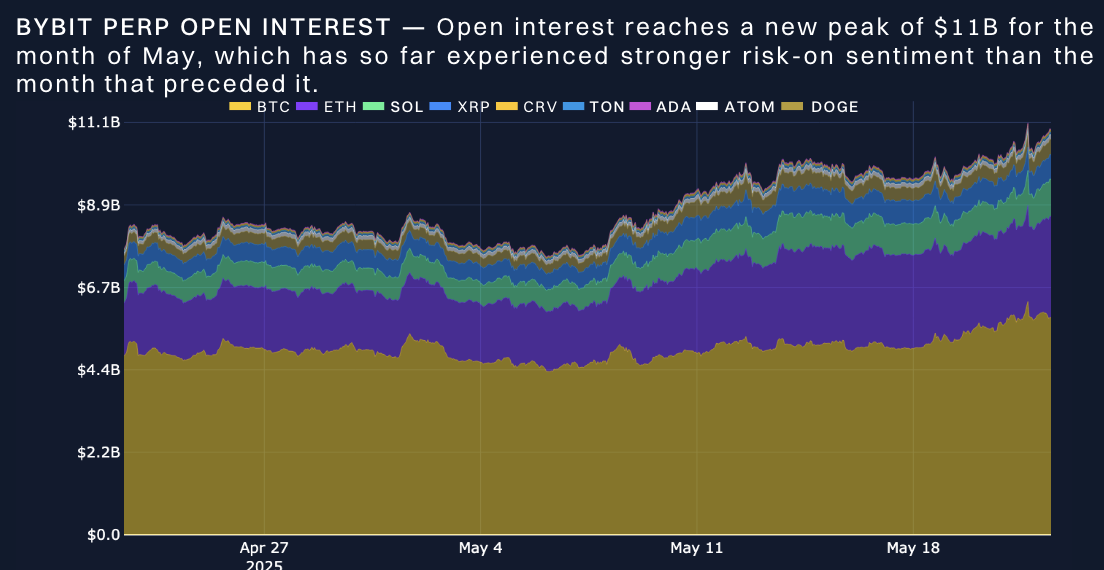
ETH open interest has started to rise this week, aligning with BTC surpassing its January ATH of $111K, positively affecting the crypto market, including Ether (+4.5%). However, the increase is slower than last week’s 50% surge in ETH's spot price. Total open interest and perpetual trading volume across nine tokens reached monthly highs of over $11B and $26B, respectively. On May 19, 2025, perpetual trading volumes surpassed $20B after Moody's downgraded US debt. BTC, like risk-on US equities, initially fell but quickly recovered its intraday losses.
Regulatory advances propel BTC toward ATH with put-call skews favouring calls
Mid-May volatility expectations declined as BTC traded sideways between $102K and $104K. Recently, this range extended to $108K due to a tariff détente between the US and China, though macro uncertainties like the downgrade of US treasuries limited a full breakout. However, regulatory advances helped BTC surpass $110K. This tug-of-war has led to reactive front-end volatility, with implied volatility levels for BTC between 45% and 50%. Options volumes remain skewed toward puts, despite the spot price entering price discovery, with open interest also dominated by puts at $200M.
What’s more, the skew of BTC volatility smiles has steepened significantly, as OTM calls trade at a higher implied volatility compared to puts across all tenors, with the one-week tenor put-call skew briefly exceeding 7% before coming back down.
ETH outperformance moderates as skews turn less bullish
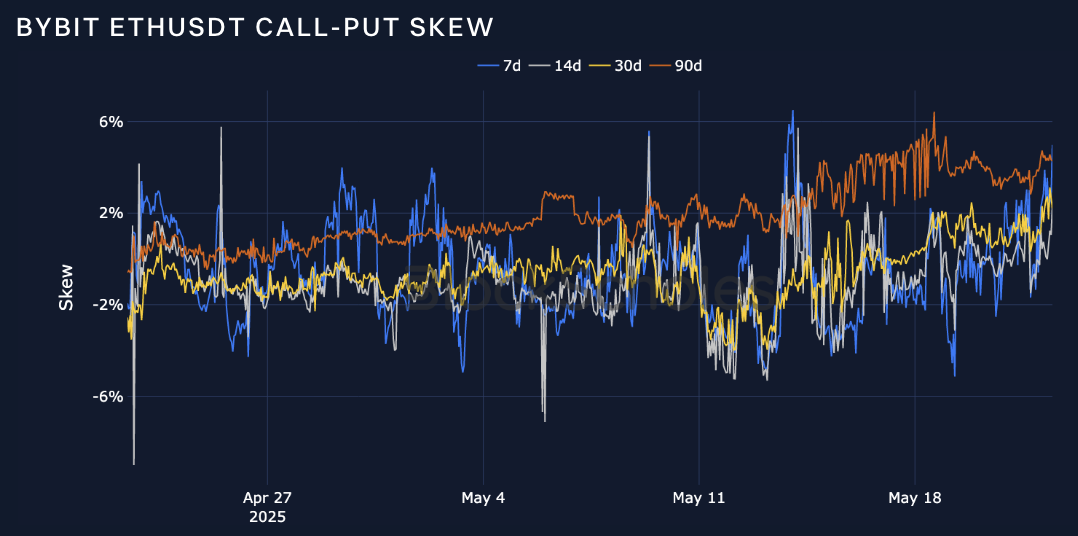
After two weeks of ETH outperformance, it now lags behind BTC. While ETH's one-month returns are an impressive 69%, its seven-day increase has been lower, largely due to BTC's recent rally. The inversion in its term structure of volatility persists, with short tenors holding a premium over longer tenors. ETH's put-call skew is now significantly less bullish than last week, though it still shows a 5% skew for OTM calls. The dominance of call options in volumes and open interest has narrowed, with open interest in calls only $30M greater than in puts.
#BybitLearn #BybitResearch
Grab Up to 100 USDT in Rewards
Also, enjoy 555% APR on Bybit Earn products!